Quick Answer
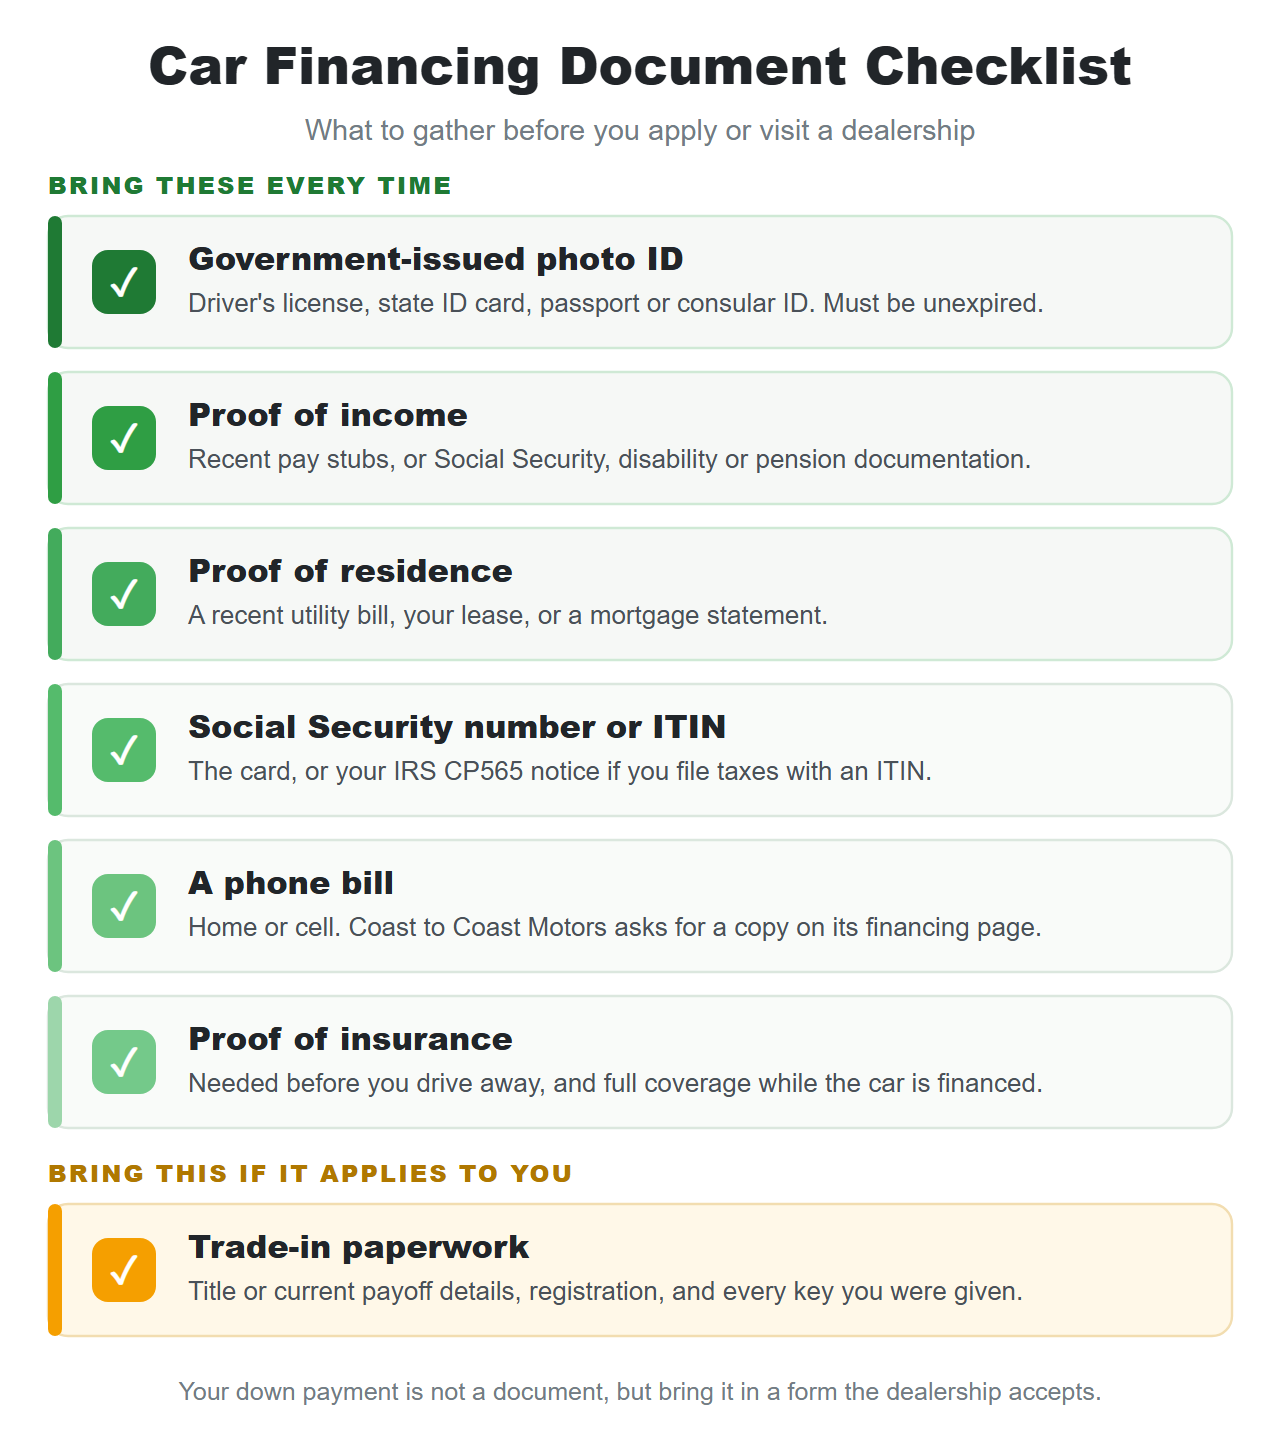
Most car financing applications require a valid government-issued photo ID, proof of income, proof of residence, and a Social Security number or ITIN — plus proof of insurance before you drive away. Coast to Coast Motors also asks for a copy of a home or cell phone bill. Recent pay stubs, or Social Security or pension documentation, satisfy income; a recent utility bill, lease or mortgage statement satisfies residence. Bring your down payment, plus the title or payoff details if you are trading in. Applying online first tells you what your file still needs.
What documents do you need to finance a car?
Most car financing applications start with four core requirements: a government-issued photo ID, proof of income, proof of residence, and a Social Security number or ITIN. Insurance is added before you drive away, and individual dealerships ask for one or two extras — Coast to Coast Motors asks for a phone bill.
The list is easier to remember as four questions than as four documents. A lender has to know who you are, what you earn, where you live and how to reach you, and every item answers exactly one of them. Once you see which question a piece of paper answers, whether a substitute will do stops being a guess. The list also varies far less between lenders than people expect — what differs is the weight. A bank tends to lean harder on the credit file, an in-house lender on what the income and residence documents show.
Government-issued photo ID, and the number that goes with it
Bring an unexpired government-issued photo ID and either your Social Security number or your ITIN. A driver's license is the usual choice, but a state ID card, a passport or a consular ID all establish identity just as well.
Two details cause more trouble than the ID itself. An expired license is not identification, and it is a common reason a buyer gets sent home. The other is the name: if your ID and your pay stub disagree — a maiden name, a missing middle initial — bring whatever connects the two.
The number is separate from the ID, and this is where buyers without a Social Security number assume they are stuck. An ITIN is a nine-digit number the IRS issues to people not eligible for an SSN; the CP565 notice confirms yours, and Coast to Coast Motors accepts one. One limit: the IRS is explicit that an ITIN does not serve as identification outside the federal tax system, so it does not replace your photo ID.
Proof of income: what counts when you don't have pay stubs
Proof of income is any document showing that money arrives regularly and can be verified by someone other than you. That definition is wider than "pay stub", and it is why being paid unconventionally is rarely the obstacle buyers expect.
Coast to Coast Motors names pay stubs, Social Security documentation and pension documentation on its financing page. Lenders also routinely accept W-2s, 1099s, bank statements, benefit statements, and — if you have just changed jobs — an offer letter stating your salary. The self-employed are usually asked for the last two years of tax returns, because a single month says little about a business.
If you are paid in cash, undeposited cash cannot be verified by anyone. Deposited cash can. Three months of statements showing money landing on a recognisable rhythm does the work of a stub — a good reason to bank cash earnings consistently before you apply.
It also helps to know what the numbers feed. Lenders compare monthly debt payments against pretax monthly income, and Experian reports that auto lenders generally prefer that ratio at 50% or less.
Proof of residence, and the phone bill most buyers forget
Proof of residence is a recent document that ties your name to your street address — a utility bill, your lease, or a mortgage statement. Coast to Coast Motors lists all three.
The word doing the work is "recent" — many dealerships ask for something from the last 30 to 60 days. The second requirement trips up more buyers: it has to be in your name. If you live with family and every bill is in a parent's name, the folder proves your parent's address. A lease listing you as an occupant, or a bill switched into your name, usually closes it. A P.O. box will not.
Then there is the item almost nobody brings unprompted. Coast to Coast Motors asks for a copy of your home or cell phone bill. It confirms the number on your application is genuinely yours — a contactability check and a quiet stability signal. Because a phone bill is usually in your own name even when the utilities are not, it is often the easiest item on the list.
Proof of insurance and your down payment
Insurance has to be in force before you drive the car off the lot, and your down payment has to arrive in a form the dealership accepts. The state minimum is liability only — 30/60/25 in Texas and 25/50/25 in Oklahoma — but while a vehicle is financed the lender holds an interest in it, so comprehensive and collision are normally required too. Call your insurer from the desk with the VIN.
Coast to Coast Motors sets down payments individually from what your application shows rather than publishing one figure for everyone. Ask which payment forms the store takes, since debit, cashier's check and cash are not always treated alike. One footnote if you are paying cash: a business receiving more than $10,000, in one transaction or related ones, must file IRS Form 8300, so expect to be asked for identifying details.
Want the number before you drive over? A free online pre-approval gives you a down payment and monthly payment based on your actual situation, so the documents you bring confirm a decision rather than start one.
Trade-in paperwork in Texas and Oklahoma
If you are trading a vehicle in, bring the title when you own it outright, or your lender's current payoff details when you do not — plus the registration and every key. Missing keys and missing titles are the two things most likely to stall a finished deal.
The two states differ in one way that surprises people who move between them. An Oklahoma title must be notarized when it is assigned, and Oklahoma also wants an odometer disclosure on vehicles from 2011 or newer and Form 718 where the title is electronic. Texas asks for the signed title with the date of sale and odometer reading, plus Form 130-U. Both require transfer within 30 days, and buying from a dealership normally means the dealership files it for you.
Where a loan is still open on the trade, ask your lender for a ten-day payoff quote rather than relying on the balance in your banking app — that figure moves with interest.
What if you're missing a document?
A missing document is usually a delay rather than a denial. Dealerships that finance their own sales handle incomplete files constantly and can often name the substitute by phone.
- No pay stub — three months of bank statements, recent 1099s, a benefit award letter, or an offer letter if the job is new.
- No utility bill in your name — a lease naming you, a bank or insurance statement mailed to the address, or a bill switched into your name first.
- No Social Security number — an ITIN, with the CP565 notice confirming it.
- No title for the trade-in — your lender's payoff quote if the loan is open, or a duplicate title from the state if it is lost.
- No insurance yet — a policy can normally be bound by phone the same day once you have the VIN.
Most rejected documents are not wrong in kind; they are out of date, in somebody else's name, or missing a page. If the gap is your credit rather than your paperwork, see our guides to what credit score you need and buying with no credit at all.
What to bring for your situation
The core list does not change, but which version of each document you bring does. These sit on top of the photo ID and SSN or ITIN everyone needs.
| Buyer situation | Documents to prepare | What may be different |
|---|---|---|
| Paid by an employer (W-2) | Two most recent pay stubs | Recency is usually the only snag. |
| Self-employed or 1099 | Two years of tax returns, recent 1099s, three months of bank statements | Income is averaged across time, so more months help you. |
| Paid in cash | Three months of bank statements showing the deposits | Cash that never reaches an account cannot be verified. |
| Retired or on benefits | Social Security, disability or pension award letter | Benefit income is regular and well documented, which counts in your favour. |
| Filing taxes with an ITIN | IRS CP565 ITIN notice alongside your photo ID | Not every dealership accepts an ITIN. Coast to Coast Motors does. |
| Living with family | Any document in your own name showing the address | Residence is the usual gap; a phone bill often solves it. |
| Trading a vehicle in | The title or a ten-day payoff quote, registration and all keys | An open loan on the trade adds a payoff step. |
How to prepare before you visit
Gather everything in one sitting the night before, and check it rather than assuming it. The buyers who finish in an afternoon are rarely the ones with the strongest files. They are the ones who opened the folder at home.
- ✓Put every document in one place — a folder, or a single album on your phone.
- ✓Check the date on the pay stubs and the utility bill before anything else.
- ✓Confirm the name and address match across all of them.
- ✓Save your insurer's number so a policy can be bound from the desk.
- ✓Request a ten-day payoff quote if you are trading in a financed vehicle.
- ✓Apply online first, so the desk is confirming your file rather than building it.
Financing at Coast to Coast Motors
Coast to Coast Motors finances its own sales, so the documents you bring are read on site by the people making the decision — the difference between an answer the same day and an answer next week.
The dealership's financing page sets out what to bring: proof of income as pay stubs, Social Security or pension documentation; proof of residence such as a recent utility bill, lease or mortgage; and a copy of a phone bill. An ITIN is accepted where a Social Security number is asked for, and monthly payment history is reported to TransUnion, so the file you are assembling is the start of a credit record rather than just a hurdle. Across the five stores in Houston, Oklahoma City and Tulsa you can browse the inventory and check which location is closest before you go.
The bottom line: financing a car takes four documents and a little checking. Confirm the dates, confirm the names match, and settle anything you are unsure about by phone before you drive over. Almost every wasted trip is a document problem, and almost every document problem is solvable at your kitchen table. If credit rather than paperwork is the worry, our guide to buying with bad credit in Texas covers that side of it.
Ready to see what you qualify for? Apply online before you visit Coast to Coast Motors to confirm which documents you need and review your financing options.
Frequently Asked Questions
What documents do I need to finance a car?
A valid government-issued photo ID, proof of income, proof of residence, and a Social Security number or ITIN cover almost every application. You also need proof of insurance before you drive away, and Coast to Coast Motors asks for a copy of a phone bill.
Can I finance a car without pay stubs?
Usually, yes. Lenders regularly accept bank statements, 1099s, the last two years of tax returns, and Social Security, disability or pension documentation. If you are paid in cash, three months of bank statements showing the deposits generally does the work a stub would.
What counts as proof of residence for a car loan?
A recent utility bill, your lease, or a mortgage statement, usually from the last 30 to 60 days, carrying your name. A bill in a parent's or partner's name proves their address, and a P.O. box will not stand in for a street address.
Can I finance a car with an ITIN instead of a Social Security number?
At dealerships that accept one, yes, and Coast to Coast Motors is among them. Bring the IRS CP565 notice confirming your ITIN. The IRS states an ITIN does not serve as identification outside the federal tax system, so it does not replace your photo ID.
Do I need insurance before I can drive the car home?
Yes. Coverage has to be in force before you leave with the vehicle, and while a car is financed the lender will normally require comprehensive and collision on top of the state liability minimum — 30/60/25 in Texas, 25/50/25 in Oklahoma.
What documents do I need to trade in a car in Texas or Oklahoma?
The title if you own the vehicle outright, or your lender's payoff details if you do not, plus the registration and every key. An Oklahoma title has to be notarized before it is assigned, which Texas does not require. Both states require transfer within 30 days.
How recent do my documents have to be?
Requirements vary by lender, but many dealerships ask for your two most recent pay stubs and a utility bill from the last 30 to 60 days. A stub from four months ago does not show you are still working.
Sources
- Coast to Coast Motors — Financing (the dealership’s own list: proof of income such as pay stubs, Social Security or pension documentation; proof of residence such as a recent utility bill, lease or mortgage; and a copy of a home or cell phone bill), and Get Approved
- Internal Revenue Service — Individual Taxpayer Identification Number (a 9-digit number for people not eligible for a Social Security number; the CP565 notice confirms the assignment; an ITIN does not serve as identification outside the federal tax system)
- Internal Revenue Service — Form 8300 and reporting cash payments of over $10,000 (filed within 15 days of a cash transaction over $10,000, in a single transaction or in related transactions; the IRS publishes motor vehicle dealership Q&As)
- Experian — Do lenders check income for an auto loan? (accepted income documentation, including 1099s, two years of returns for the self-employed, bank statements and benefit statements; auto lenders prefer a debt-to-income ratio of 50% or less)
- Texas Department of Motor Vehicles — Buying or selling a vehicle (title transferred into the buyer’s name within 30 days; Form 130-U; lien release where applicable; the dealership files the title when you buy from a dealer)
- Service Oklahoma — Vehicle titles (a properly assigned and notarized Oklahoma title, Form 718 for an electronic title, lien release, insurance verification, and an odometer disclosure for 2011 or newer vehicles; transfer within 30 days)
- Texas Department of Insurance — Auto insurance guide (30/60/25 minimum liability; collision and comprehensive required while the vehicle is financed)
- Oklahoma Insurance Department — Auto insurance: common myths (25/50/25 minimum liability; full coverage commonly required on financed vehicles)